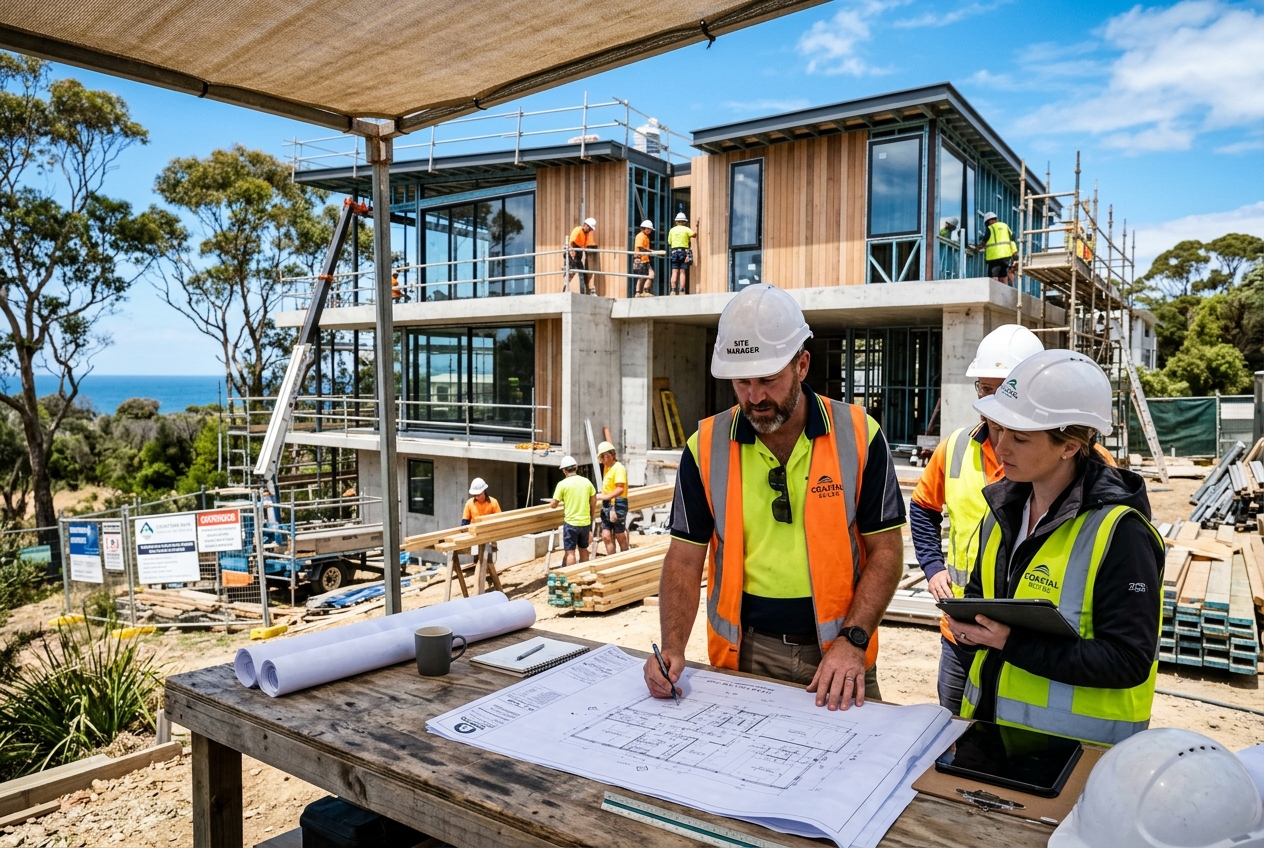
Building a new home is one of the biggest financial commitments you can make. From purchasing the land and finalising your building contract to managing progress payments and staying within budget, there are a lot of moving parts. A construction loan is designed differently from a standard home loan, with funds generally released progressively as your home is built. At Brighton Finance, we help you understand how construction finance works, assess your borrowing position and compare suitable lending options across our lender panel. Whether you're building your first home, creating your next family home, constructing an investment property or planning a knockdown rebuild, we'll help you understand your options and guide you through the finance process.
Before construction begins, your lender will assess your financial position, the proposed property and the construction project. Once your loan is approved and construction starts, funds are generally released to your builder in stages.
The stages and payment requirements can vary depending on your builder, building contract and lender. We can help you understand how your chosen lender structures construction finance before you proceed.
A typical construction project may involve:
01. Land Purchase: If you're purchasing land to build your home, your finance may be structured to include the land purchase as part of your overall lending arrangement.
02. Foundations: Once site preparation and foundation work have been completed, the first construction progress payment may be requested.
03. Frame: A further payment may be released once the structural frame of the property has been completed.
04. Lock-Up: Once the property reaches the lock-up stage, another progress payment may be made.
05. Fixing: This stage generally involves internal work such as cabinetry, doors, fixtures and other fittings.
06. Completion: The final progress payment is generally made once construction is substantially complete and the lender's requirements have been satisfied.
What Are Construction Loan Progress Payments?
Paying for your build as work is completed.
Progress payments are staged payments made to your builder as different parts of your construction are completed. Instead of you receiving the full amount at once, the lender releases it in stages. This can help align your finance with the construction schedule.
Before each payment, the lender may require confirmation that the relevant stage has been completed and may have specific documentation, valuation or inspection requirements.
Understanding this process before construction starts is important because delays in providing the required information can potentially affect the timing of payments to your builder. Your lender's specific progress payment requirements will depend on the construction contract and loan arrangement.
How Much Can You Borrow to Build a Home?
Start with what you can comfortably afford.
The amount you can borrow for your construction project depends on your individual financial circumstances and the lender's assessment criteria.
It's important to understand your borrowing position before committing to land, a builder or a construction contract. At Brighton Finance, we'll assess your broader financial position and help you understand what may be achievable before you move ahead.
Lenders may take into account:
Your income
Living expenses
Existing home loans and other debts
Credit card limits
Number of dependants
Deposit and available savings
Land value
Construction costs
Proposed property value
Your employment or business structure
The lender's servicing and credit policies
How Much Deposit Do You Need?
There isn't one deposit amount that applies to every construction loan.
Before committing to your project, we can help you understand the broader financial picture.
The deposit you need can depend on factors such as:
The value of the land
Total construction costs
The expected value of the completed property
Your income and financial position
The lender's lending criteria
Whether you're eligible for any relevant government schemes or concessions
Stamp duty
Conveyancing and legal costs
Building and design costs
Planning and permit fees
Site costs
Inspections
Lender fees
Insurance
Other professional and project costs
Construction Loans for a Knockdown Rebuild
Turn your existing property into your next home.
A knockdown rebuild can be an attractive alternative to selling your existing property and purchasing elsewhere. Instead of renovating an unsuitable home or moving to a new suburb, you may be able to demolish the existing house and construct a new home on the same block.
If you're considering a knockdown rebuild in Perth, it's worth understanding the finance implications before committing to your plans.
These may include:
Your existing mortgage
Current property value
Demolition costs
Construction costs
The value of the completed property
Temporary accommodation during construction
Existing financial commitments
Construction timeframes
Construction Loans for First Home Buyers
Building your first home is a big step. Your finance shouldn't be confusing.
If you're a first home buyer, building can give you the opportunity to create a home specifically for your needs. But combining a land purchase, construction contract, deposit and loan application can feel overwhelming.
We'll explain the process clearly and help you understand your options before you commit.
We can help you understand:
How much you may be able to borrow
How your land purchase may be financed
How construction progress payments work
What documentation you'll need
What costs you should allow for
How your construction finance may be structured
Construction Loans for Investors
Build with your investment strategy in mind.
Building an investment property can be an important part of a broader property strategy. Whether you're constructing your first investment property or adding to an existing portfolio, the finance structure needs to take your current position and future plans into account.
We can help you explore construction finance options while considering factors such as your existing loans, borrowing capacity, investment objectives and overall financial position.
Construction Loans for Self-Employed Borrowers
If you're self-employed, your income may not always look as straightforward as a PAYG employee's. Business structures, company income, trust distributions, retained profits and variable income can all create additional considerations when applying for finance.
Brighton Finance understands the realities of running a business. We'll work with you to understand your financial position and explore lenders whose assessment criteria may be suitable for your circumstances.
What Do You Need for a Construction Loan?
Getting your documents ready can make the process smoother.
Having the right information available early can help your broker and lender assess the application more efficiently. We'll let you know what is required based on your individual circumstances.
The exact requirements vary between lenders and applicants, but you may need documents such as:
Identification
Evidence of income
Recent payslips or business financial information
Details of existing debts and financial commitments
Land contract, if applicable
Building contract
Building plans and specifications
Detailed construction costs
Information about your builder
Evidence of your available funds
Other documents requested by your lender
What Happens If Construction Costs Change?
Plan carefully. Stay informed.
Construction projects don't always go exactly according to plan. Changes to your building specifications, variations to your contract, unexpected site costs or increases in construction costs can affect the total amount required to complete your home.
This is why it's important to understand your available funds before construction begins.
If your circumstances or project costs change during construction, speak with your broker as early as possible. Depending on the situation, additional finance may require further assessment and lender approval. Don't assume additional construction costs will automatically be covered by your existing loan.
Why Brighton Finance?
Finance advice built around your bigger picture.
At Brighton Finance, we don't believe in treating construction finance as simply another loan application. We start by understanding your plans, your financial position and what you're ultimately trying to achieve.
Personalised Advice: Your construction project is unique. We tailor our advice to your circumstances rather than applying a one-size-fits-all approach.
Access to Choice: We have access to an extensive panel of Australian lenders, giving us the ability to compare suitable lending options.
Clear Communication: We explain the finance process in straightforward language and keep you informed along the way.
Real-World Experience: Founder and Principal Mortgage Broker Chintan Shah brings experience not only in mortgage broking, but also as a homeowner and business owner.
Long-Term Support: Your relationship with Brighton Finance doesn't have to end when your home is finished. As your circumstances and financial goals change, we're here to help you review your options.
How we help
A clear path from first conversation to the next decision.
01
Start With a Conversation
Tell us about your plans, whether you're purchasing land, have already secured a block or are preparing to build.
02
Understand Your Position
We'll assess your income, commitments, deposit and broader financial position to understand your borrowing capacity.
03
Develop Your Finance Strategy
We'll consider the structure of your proposed project and identify suitable lending options.
04
Compare & Recommend
We compare available options and explain the key differences so you can make an informed decision.
05
Prepare Your Application
We'll help you understand the required documentation and prepare your application for submission.
06
Manage Approval
We'll liaise with the lender and help manage the application through the approval process.
07
Construction & Progress Payments
Once construction begins, funds are generally released progressively according to the lender's requirements and construction stages.
08
Completion
As construction reaches completion, the final progress payment is made in accordance with the lender's requirements and your loan transitions into its ongoing structure.
Frequently asked questions
Useful answers before you begin.
These answers are general. Lending policy, costs and eligibility depend on the application and can change.
Can I get a construction loan to build my first home?+
Yes. Construction finance can be available to eligible first home buyers, subject to lender criteria and your financial circumstances.
Can I buy land and build a home?+
Yes. Depending on your circumstances and the lender, finance may be structured to include both the land purchase and construction.
Do I receive the entire construction loan upfront?+
Generally, construction funds are released progressively rather than all at once. The lender releases funds as agreed stages of construction are completed.
What are construction progress payments?+
Progress payments are staged payments made to your builder as different stages of your home are completed.
How many progress payments are there?+
The number and timing of progress payments can vary depending on your building contract, builder and lender.
Can I build an investment property?+
Yes. Construction finance may be available for investment properties, subject to lender criteria.
Can self-employed people get construction loans?+
Yes. Self-employed applicants can apply for construction finance. However, lenders may have different requirements for verifying self-employed income and assessing borrowing capacity.
Can I get a construction loan for a knockdown rebuild?+
Potentially, yes. Knockdown rebuild finance can involve additional considerations, particularly if you already have a mortgage on the property.
Can I use a construction loan for renovations?+
Some lenders offer finance options for substantial renovations or construction work. The appropriate loan structure depends on the scope of the project and your circumstances.
Do I pay interest on the full loan amount during construction?+
Construction loans generally involve progressive drawdowns, meaning the amount outstanding increases as funds are released. Your interest costs will therefore depend on the amount drawn and the terms of your loan.
What happens if my construction project is delayed?+
Construction delays can affect your project and potentially your finance arrangements. If you expect a delay, speak with your broker and lender as early as possible to understand the applicable requirements.
Can I change my building contract after loan approval?+
Changes to your construction contract or project costs may affect your approved finance. Discuss significant changes with your broker and lender before proceeding.
Start a conversation
Ready to Start Building?
Let's put the right finance behind your plans. Whether you're still exploring your options, have already purchased land or are ready to start construction, Brighton Finance can help you understand your construction finance options. Tell us about your project and let's start with a conversation.
Credit assistance is subject to lender criteria, verification and approval. Information on this page is general and does not take account of your objectives, financial situation or needs.